Skip to content

Every transaction, accounted for

FinTech products built for regulators, investors and users

From payment apps to lending and wealth platforms, we build fintech products with secure onboarding, clean ledgers and the audit trails your partners expect.

Engineering for money movement

Fintech covers payments, digital lending, wallets, wealth management, personal finance and the infrastructure behind them. Every one of these products moves money or makes decisions about it, so a missed edge case is not a cosmetic bug. Ledger accuracy, idempotent transactions, fraud checks and clear reconciliation matter as much as a smooth onboarding screen.

We work with fintech founders, NBFCs launching digital products and established companies adding embedded finance. Indian products often need KYC flows, UPI or payment gateway integration through licensed partners, account aggregator consent and alignment with RBI digital lending guidelines. Products for other markets bring their own rules, and we plan for them before the architecture is fixed.

Nexzem builds fintech platforms with double-entry ledgers, role-based access, encrypted personal data and detailed audit logs from the first sprint. We integrate with your chosen banking, KYC and payment partners rather than locking you into ours. Your team receives full source code, infrastructure scripts and documentation so investors and auditors can review what was built.

What a payment passes before it settles

Change the amount and payee and watch an illustrative set of checks decide whether a payment goes through.

What FinTech teams get with Nexzem

Scroll along the line: each outcome lights up as the signal reaches it.

  1. Audit-ready from day one

    Every money movement is logged with who, what and when, which shortens partner bank and investor diligence.

  2. Partner-neutral integrations

    We connect to the payment, KYC and banking partners you choose, so switching a vendor later does not mean a rewrite.

  3. Faster path to launch

    A phased roadmap gets a compliant first version in front of users while advanced features follow in later sprints.

  4. Security as a habit

    Encrypted data, secret management, OWASP-aligned code reviews and penetration test support are part of every release.

FinTech software we build

Payment, lending, wallet and wealth apps for fintech startups, built secure from the first commit.

Payment and wallet apps

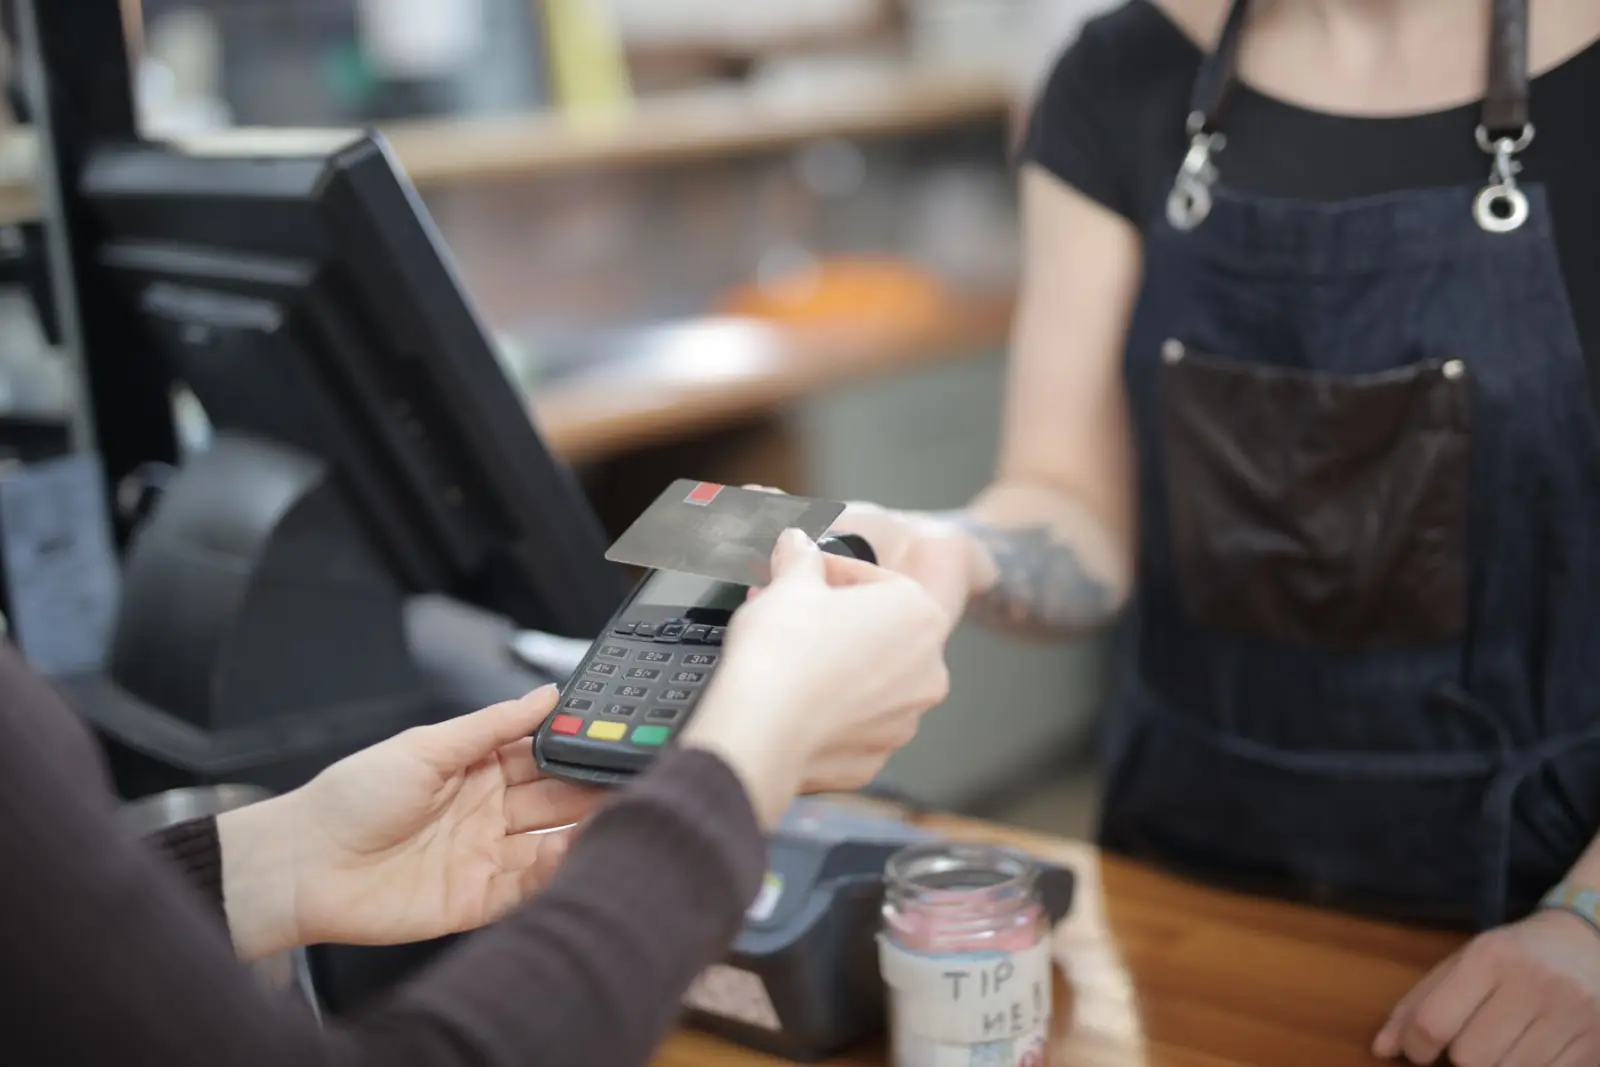
Wallets, UPI payments through partner PSPs, bill payments and merchant collections with real-time status, refunds and reconciliation reports for finance teams.

Every build includes

  • Audit-ready from day one
  • Partner-neutral integrations
  • Faster path to launch
  • Security as a habit

Regulations fintech products must account for

In India, the RBI's digital lending guidelines require loans to be disbursed directly into the borrower's bank account and repaid directly to the lender, with a key fact statement showing the full cost of credit and disclosure of every lending service provider involved. Payment aggregators need RBI authorization, payment system data must be stored in India under the RBI's localization rules, and onboarding must follow the KYC Master Direction, which permits video-based customer identification.

Card data brings PCI DSS obligations, and products serving Europe face PSD2 strong customer authentication and the GDPR. Rules change often, so architecture should make consent screens, disclosures, limits and partner configurations editable without new releases. This is general information, not legal advice; your compliance team or counsel should confirm what applies to your license and partners.

  • Store key fact statements and consent records for every loan.
  • Keep payment system data on servers located in India.
  • Log every partner API request and response for audit.
  • Separate customer funds from operating money in the ledger design.
  • Make limits, fees and disclosures configurable by compliance staff.
  • Version every policy document customers accept, so you can show what they agreed to.

Build, partner or license: choosing your stack

Few fintech startups hold every license themselves. Most partner with a bank or regulated NBFC for lending or accounts, use payment gateways such as Razorpay, Cashfree or Stripe for collections, and call specialist APIs for KYC, credit bureaus, bank statement analysis and account aggregator data. Partnering gets you to market faster, while owning more of the stack gives control over margins and customer experience later.

The architecture should keep partners swappable. Put each external provider behind your own internal interface, keep the ledger and customer records in your system, and store every request and response for audit. When a partner changes pricing, fails an audit or goes down, you can switch without rewriting the product.

Plan for scale in the ledger from the start. A double-entry ledger with immutable entries, idempotent transaction APIs and daily reconciliation against bank and gateway files prevents the silent mismatches that become painful at higher volumes and during audits. Fixing ledger design after launch is expensive.

Where AI fits in fintech

Common uses include fraud and anomaly detection on transactions, credit models that add alternative data to bureau scores, collections prioritization, document extraction from bank statements and salary slips, and support assistants that answer account questions. Each needs explainable decisions, fairness testing across customer groups, human review for adverse outcomes and monitoring, because regulators and customers will ask why a loan was declined or a payment blocked.

Start with problems where data already exists and outcomes appear quickly, such as transaction fraud or document extraction. Credit models need longer validation, because loan performance takes months to observe, so run them in shadow mode alongside existing rules before letting them influence approvals.
How we build for FinTech

Clear stages with a review at the end of each, so you always know what happens next and what it costs.

  1. 01

    Product and compliance scoping

    We map your money flows, partners and the regulations that apply before choosing an architecture.

  2. 02

    Ledger and data design

    We model accounts, transactions and states first, because every later feature depends on getting this right.

  3. 03

    UX for trust

    Onboarding and payment screens are prototyped and tested so users understand fees, status and next steps.

  4. 04

    Sprint delivery

    Working features ship every two weeks against partner sandboxes, with automated tests on every transaction path.

  5. 05

    Launch and scale

    We support partner certification, production rollout and monitoring, then tune performance as volumes grow.

FinTech use cases

  1. Buy now, pay later at checkout

    An ecommerce partner offers instant credit at checkout. The platform runs eligibility checks, shows a key fact statement, sets up repayment mandates and settles merchants, while the lending partner sees every loan in its own reporting.

  2. Recurring savings with UPI AutoPay

    Users set weekly or monthly savings goals funded through UPI AutoPay mandates, track progress in the app and withdraw anytime, with reconciliation jobs matching every debit and payout against bank statements each day.

  3. Expense management for small businesses

    Employees capture receipts with their phones, the app extracts amounts and GST details, managers approve on mobile and finance exports clean entries to accounting software, replacing month-end spreadsheet chasing and lost paper receipts.

  4. Invoice financing marketplace for MSMEs

    Suppliers upload approved invoices from large buyers, lenders bid to finance them, and the platform handles verification, agreements, disbursement and repayment tracking with a complete audit trail for every party.

Technology behind our FinTech software

Proven, well-supported tools chosen for your scale, budget and team, never for novelty.

  • React
  • Next.js
  • Flutter
  • Node.js
  • Java
  • Spring Boot
  • PostgreSQL
  • Redis
  • Kafka
  • AWS

FinTech software FAQs

Something else on your mind? Ask a consultant and get a reply within one business day.

What drives the cost of a fintech app?

The main drivers are the product type, the number of partner integrations such as KYC, payment gateways and banks, ledger complexity, admin tooling and the security testing required. We give a fixed quote once a free consultation has clarified scope and partners.

Can you integrate UPI and payment gateways?

Yes. We integrate payment gateways such as Razorpay and Stripe, and UPI flows through licensed PSP or bank partners. Direct UPI access requires NPCI and bank relationships, so we work with the partner you have or help you shortlist one.

How do you handle security for financial data?

We encrypt data in transit and at rest, store secrets in managed vaults, enforce role-based access with maker-checker approvals and keep immutable audit logs. We also support third-party penetration testing before launch and fix findings within the engagement.

Do you follow RBI guidelines?

We design products to align with applicable RBI directions, such as digital lending guidelines on disclosures and fund flows, and KYC norms for onboarding. Regulatory responsibility stays with the licensed entity, so we work alongside your compliance advisor on interpretation.

How long does it take to launch an MVP?

A focused fintech MVP with onboarding, one core money flow and an admin console typically takes 12-16 weeks. The timeline depends heavily on how quickly partner sandboxes and approvals come through.

Do we need our own RBI license to launch a fintech product?

Not always. Many products launch by partnering with a licensed bank, NBFC or payment aggregator, with the fintech acting as a technology or lending service provider. The right model depends on whether you hold funds, lend from your balance sheet or process payments, so get regulatory advice early.

How do you test payment and lending flows before launch?

We use partner sandboxes, automated tests for every money movement path including failures and retries, reconciliation tests against simulated bank files, and a closed beta with real but limited transactions. Ledger balances are checked automatically after every test run.

We work with clients across the USA, UK, Australia, UAE, New Zealand and India.

Where we work

Software that fits how your sector works.

Share your workflows and compliance needs. We reply within one business day with a suggested approach and team.